Growth can look healthy on a sales chart while creating pressure everywhere else. A larger order book may require more inventory, additional staff, new equipment, or longer payment terms before the related cash reaches the bank. Financial planning helps a business see that sequence before committing to it.
At its best, financial planning is not a document prepared for a lender and then filed away. It is a working system that connects commercial goals with cash requirements, profitability, financing capacity, and measurable progress. That connection gives owners and managers a better basis for deciding when to invest, when to wait, and what assumptions need to change.
Financial planning turns ambition into resource requirements
A strategic goal such as entering a new market sounds straightforward until its financial requirements are mapped out. The business may need research, marketing, specialist staff, technology, inventory, training, or a larger premises. Some costs arrive immediately, while the revenue they support may develop gradually.
A financial plan translates the goal into questions that can be tested:
- What investment is required before the initiative produces revenue?
- Which costs are fixed, and which rise with sales volume?
- How quickly are customers expected to pay?
- What level of sales is needed to cover the additional costs?
- How will the plan affect working capital and existing obligations?
The U.S. Small Business Administration recommends linking financial projections to the underlying business plan and explaining the assumptions behind projected revenue, expenses, capital expenditure, and funding needs. Its guidance also distinguishes between longer-range projections and more detailed first-year forecasts, which may be prepared monthly or quarterly. That distinction is useful: a long-term direction needs a shorter-term operating schedule to become actionable.
Cash flow is the constraint that profit can hide
Profit and cash are related, but they do not arrive on the same timetable. A sale can be recorded before the customer pays. Equipment may be purchased before it contributes to revenue. A fast-growing company can therefore have improving sales and still face a short-term cash deficit.
This is why a growth plan should include more than a projected income statement. A practical set of forecasts commonly includes:
| Planning view | What it helps explain | Useful planning question |
|---|---|---|
| Income statement | Revenue, costs, expenses, and projected profit | Will the initiative become economically sustainable? |
| Cash-flow forecast | Timing of receipts, payments, financing, and cash balances | Can the business fund the plan as it unfolds? |
| Balance-sheet forecast | Assets, liabilities, equity, and working-capital effects | How will the plan change the financial position? |
| Capital-expenditure budget | Major purchases and their timing | Which assets are necessary, and when should they be acquired? |
Planning structure based on guidance from the U.S. Small Business Administration and Business Development Bank of Canada.
For a business with uneven receipts or significant inventory commitments, a rolling short-term forecast can be especially valuable. BDC describes a 13-week cash-flow forecast as a way to gain tighter visibility over near-term inflows and outflows, while its broader financial-planning guidance recommends comparing forecasts with actual results and updating them as conditions change.
The practical lesson is simple: growth should be paced according to the cash cycle, not only according to demand. A company may have a strong commercial opportunity and still need to stagger hiring, negotiate supplier terms, adjust customer payment policies, or arrange financing before accepting additional volume.
Scenario planning makes assumptions visible
Every forecast contains assumptions. Sales may be based on a conversion rate, an expected price, a number of customers, or a capacity limit. Costs may depend on wages, supplier prices, rent, energy, logistics, or borrowing terms. Writing those assumptions down makes the plan easier to challenge and improve.
Scenario planning then shows how the result changes when important inputs move. A business might compare a base case with a slower sales ramp, higher material costs, delayed customer payments, or a larger-than-expected staffing requirement. This is not an attempt to predict the future precisely. It is a way to identify which conditions would matter most and what response would be available.
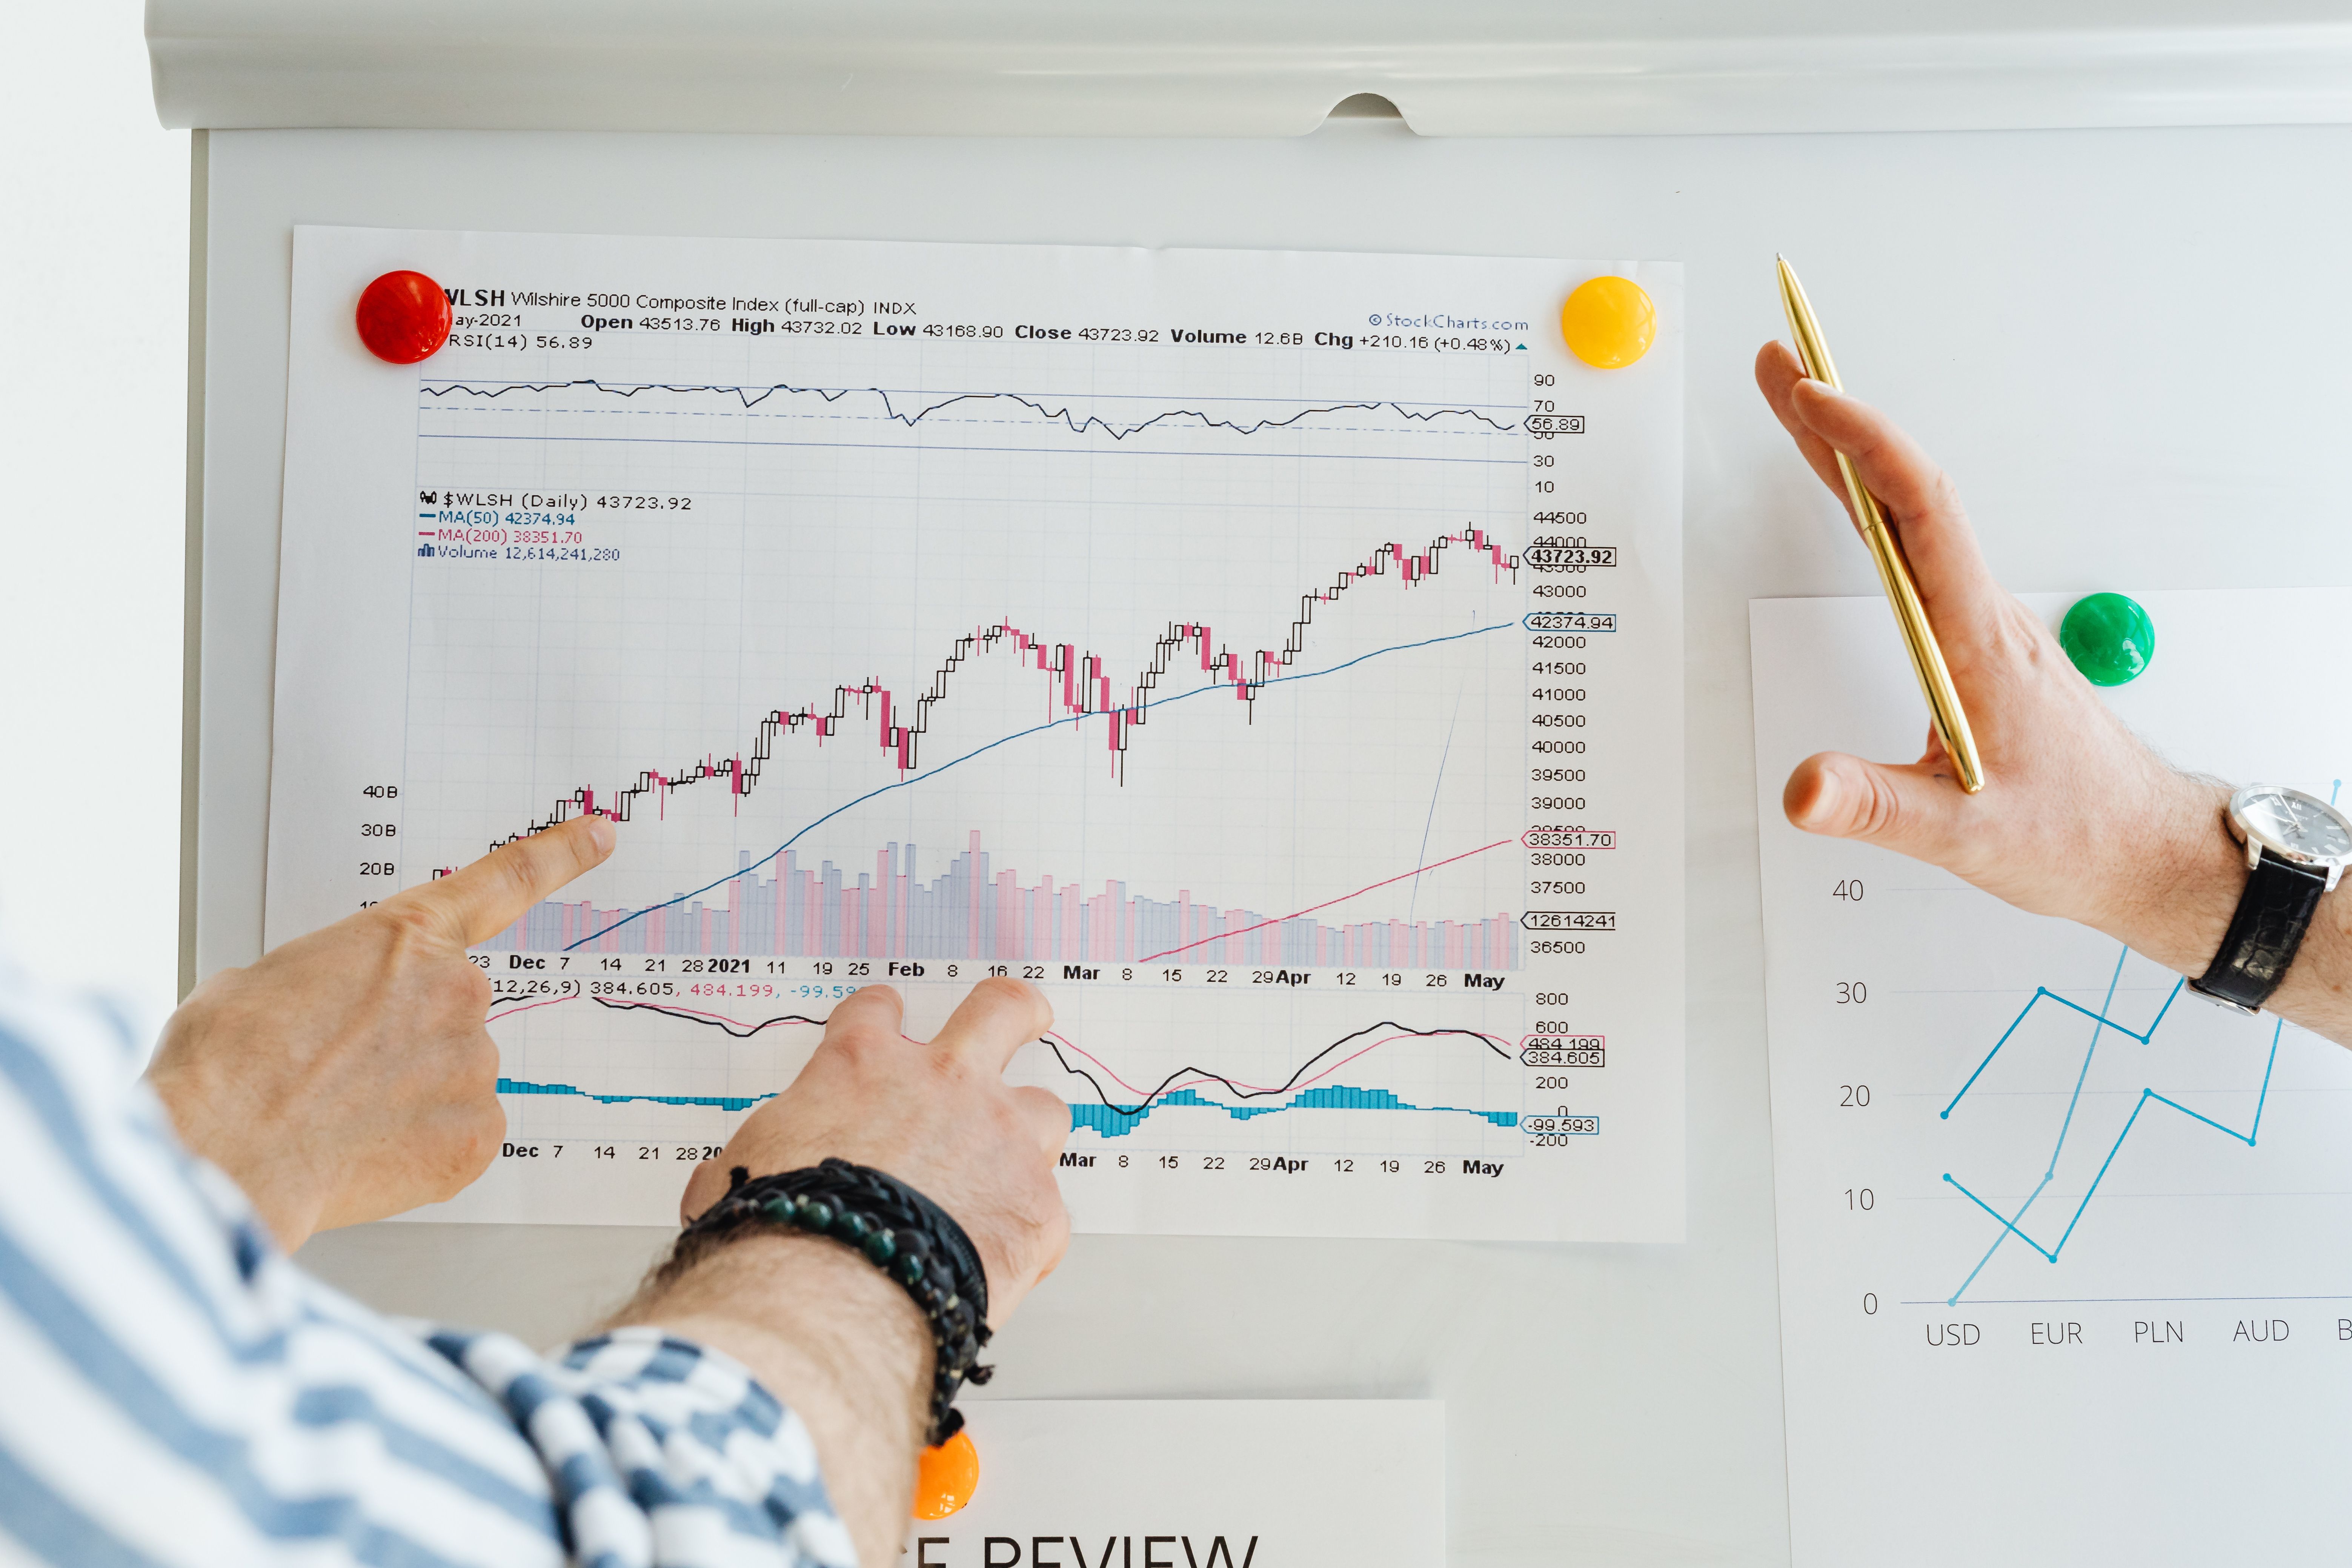
BDC’s guidance on sensitivity analysis highlights sales and gross margin as important variables for many businesses, while also stressing the need to examine liquidity alongside profitability. That distinction matters. A change may leave projected annual profit intact but create a cash shortfall at an inconvenient point in the operating cycle.
My practical preference is to keep scenarios limited and decision-oriented. Three cases can be enough when each one answers a specific question: what happens if demand is slower, costs are higher, or payment arrives later? A spreadsheet with dozens of variations can create the appearance of precision without improving the decision.
Financial planning improves capital allocation
Businesses rarely have unlimited money, staff time, or management attention. Financial planning provides a framework for comparing competing uses of those resources. A proposed product launch, a new location, upgraded equipment, additional sales staff, and process automation may all sound worthwhile; the plan helps show their expected timing, funding requirement, risk, and contribution to the wider strategy.
The comparison should not rely on revenue alone. Useful measures may include contribution margin, payback period, working-capital demand, capacity utilization, customer retention, and the operational dependencies created by the investment. A project with attractive projected revenue may be less suitable than a smaller project if it requires a level of funding or execution capacity the business does not currently have.
The IFRS Foundation’s current management-commentary framework gives a useful broader perspective: decision-useful reporting should connect a business model, strategy, resources, risks, financial performance, and future cash flows. Although that framework is designed for financial reporting, the underlying discipline also helps private businesses explain why a particular investment supports their long-term direction. Clear business reporting similarly benefits from showing how resources and objectives relate to one another, rather than presenting isolated numbers.
Review turns a plan into a management habit
A forecast becomes more useful when actual performance is compared with it on a regular schedule. The purpose is not to punish a plan for being wrong. It is to understand why the result differs and whether the underlying assumption, the execution, or the external environment has changed.
A monthly review might examine:
- Actual sales compared with the forecast, including volume and pricing.
- Gross margin and the main causes of any movement.
- Receivables, payment timing, and overdue balances.
- Inventory or work-in-progress tied up in the operating cycle.
- Hiring, supplier, and capital-spending commitments.
- Cash available for planned investments and contingencies.
Each material variance should lead to a decision or a revised assumption. If sales are below plan because a channel is taking longer to develop, the business may defer related hiring. If demand is stronger than expected, it may need to secure working capital before capacity becomes the bottleneck. In both cases, the value lies in acting early rather than waiting for year-end accounts to reveal the full picture.
Growth needs financial resilience, not just expansion capital
Long-term growth also depends on the ability to absorb setbacks. A financial plan can identify the obligations that continue during a slow period, the commitments that cannot easily be reversed, and the amount of liquidity needed to keep operating while a strategy is adjusted.
That resilience may involve maintaining a cash buffer, arranging an appropriate credit facility, diversifying suppliers, staging capital purchases, or defining thresholds that trigger a review. The right approach depends on the business model, sector, financing arrangements, and risk tolerance. There is no universal reserve figure that fits every company.
BDC’s guidance on planning and modelling emphasizes that projections should be updated when conditions change rather than treated as an annual exercise. This is a useful standard for growing businesses: the plan should become more accurate through repeated comparison with real operating data.
A repeatable cycle for sustainable growth
Financial planning supports long-term business growth through a repeatable cycle:
- Define the strategic objective and the evidence that would show progress.
- Translate the objective into revenue, cost, staffing, asset, and cash assumptions.
- Build linked income-statement, cash-flow, and balance-sheet projections.
- Test the plan against a small number of meaningful scenarios.
- Choose investments according to strategic fit, return potential, timing, and funding capacity.
- Compare actual performance with the forecast and revise the plan when facts change.
The strongest financial plan is not the one with the most elaborate formulas. It is the one that helps a management team see the next constraint, recognize the assumptions carrying the most risk, and make a timely adjustment. That is how financial planning turns growth from a hopeful target into a process the business can fund, measure, and sustain.